
Landlord Insurance, California 2026
Primary hazards, required endorsements, and FAIR plan availability for California rental properties
The moment you rent out a California property, the homeowner policy on it stops doing its job. Insurers price and word an owner-occupant policy for someone who lives in the home, and a tenant changes the risk enough that the wrong policy can leave you holding a mortgage on a burned lot. The policy built for rentals is the dwelling fire form, usually a DP-3, and in California it now sits inside a market reshaped by wildfire, the state FAIR Plan, and rate increases that landed in 2026.
No California statute forces you to insure a rental. The pressure comes from your lender: a mortgage almost always requires property coverage in an amount tied to the loan, and federally backed loans require it outright. This page covers how a landlord policy differs from a homeowner policy, when coverage is effectively mandatory, and the state-specific risk factors, wildfire above all, that move the premium.
Primary Hazards for California Landlords
DP-3 vs. a homeowner policy: what actually changes
A homeowner policy (HO-3) and a landlord policy (DP-3) both insure a house, but they solve different problems. The DP-3 is an open-peril form, it covers any structural loss unless the cause is specifically excluded, which is the same broad footing as an HO-3. Its cheaper cousins, the DP-1 and DP-2, are named-peril forms that only pay for a listed set of causes, and most landlords want the DP-3 for that reason.
The pivotal difference is in the income and occupancy provisions. A homeowner policy includes Loss of Use, which pays for your hotel while your home is repaired. You don't live in a rental, so that coverage is replaced by Fair Rental Value, which reimburses the rent you lose while a covered peril makes the unit uninhabitable. Miss that swap and a fire that empties your building for six months costs you six months of rent with no offset.
The occupancy detail is not a technicality. Leaving an owner-occupant HO-3 in place after you move a tenant in is material misrepresentation. On a large claim the insurer can run a residency check, deny the loss, and void the policy for the misstatement, the worst possible outcome on a total loss. Switching to a landlord form is what keeps the coverage enforceable.
Is it required? Lenders, not the state
California does not have a law requiring a landlord to carry insurance on a rental property. The requirement is contractual. Any mortgage lender will require hazard/property coverage at least equal to the loan or replacement cost, name itself as mortgagee, and can force-place expensive coverage if yours lapses. Loans backed by federal programs require property insurance as a condition of the loan.
Two separate coverages are commonly demanded on top of the base structure policy. Liability coverage protects you when a tenant or guest is injured and sues, it is not legally mandated in California but is standard on any landlord policy and often required by lenders and by tenants' own leases. Flood coverage is mandatory, by federal rule, when a federally backed mortgage sits on property inside a FEMA Special Flood Hazard Area; a landlord or DP-3 policy excludes flood entirely, so that protection has to come from a separate NFIP or private flood policy.
One practical upside: because a rental is a business, the premium is a deductible expense. Landlord insurance is generally fully deductible as an ordinary operating cost on Schedule E, alongside mortgage interest, depreciation, and repairs.
The California risk factors that drive cost
Nationally, insurers treat a rental as roughly a quarter more expensive to cover than an owner-occupied home, landlord policies commonly run about 25% more than a comparable homeowner policy, reflecting tenant occupancy, vacancy gaps, and added liability. That is the baseline before California's own hazards are priced in.
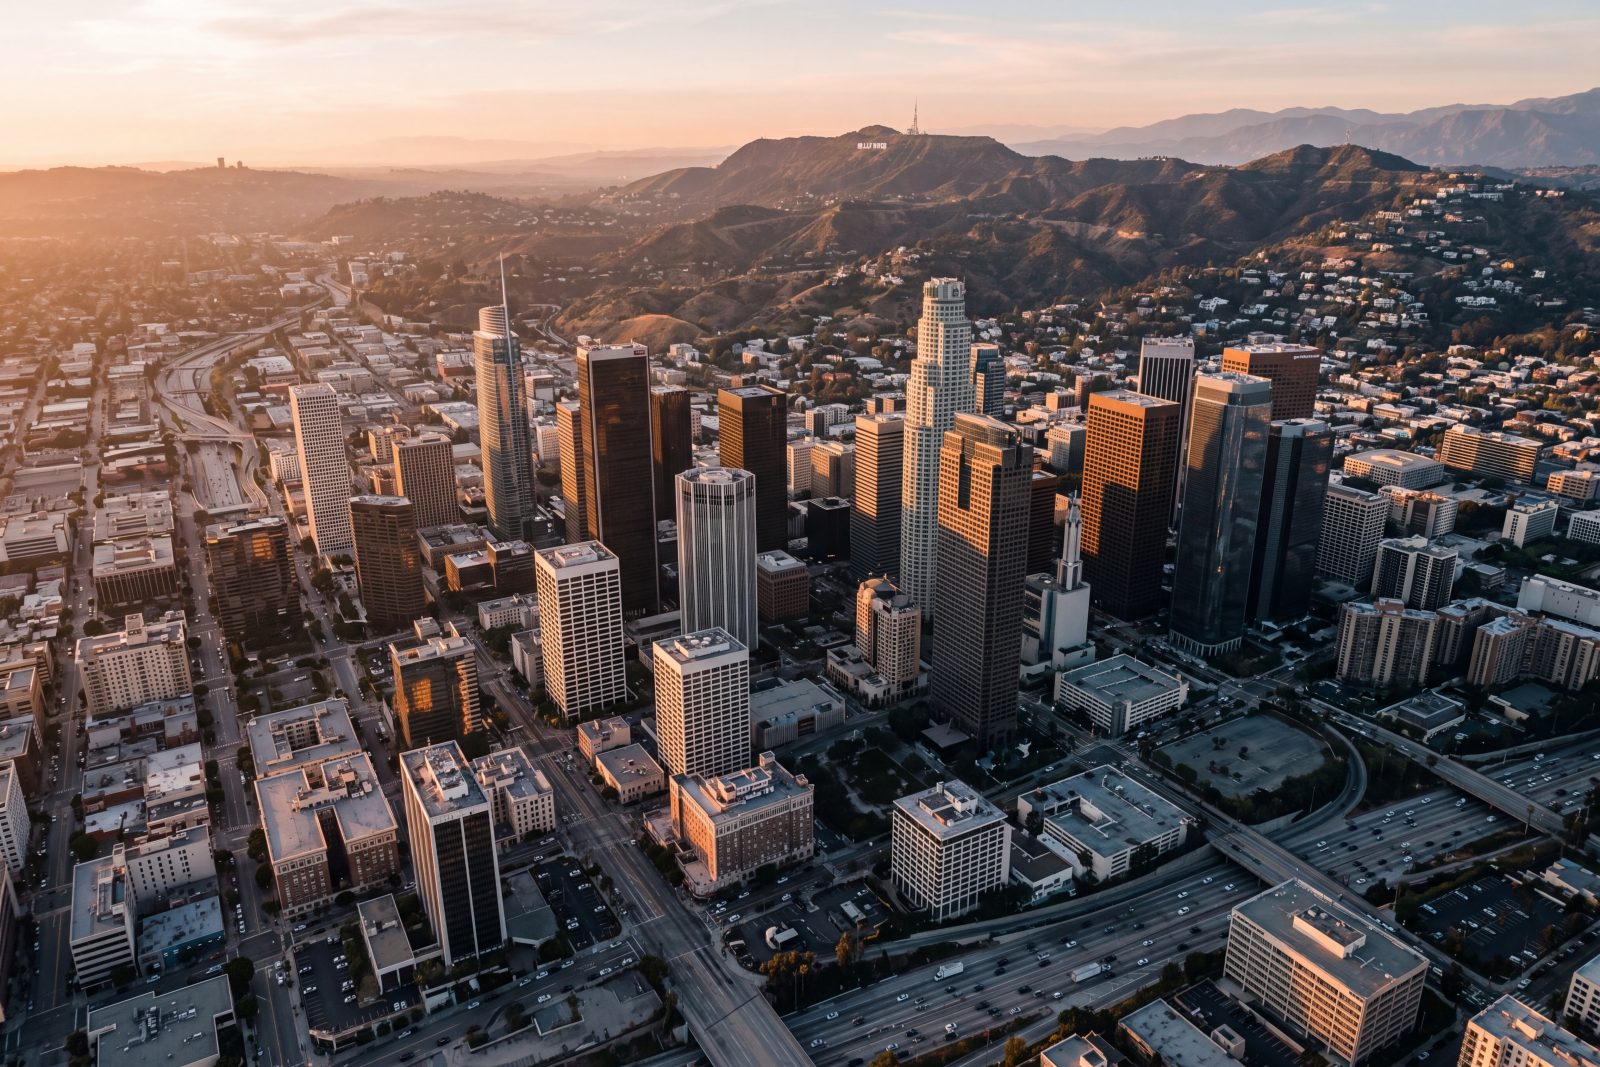
In California, the dominant factor is wildfire. Properties in or near the wildland-urban interface are increasingly non-renewed by admitted carriers, which pushes owners toward the FAIR Plan or the surplus-lines market at materially higher cost. Flood is a distinct, separately priced exposure handled through the NFIP, not the property policy. Coastal and inland liability exposure, the age and construction of the building, and whether the unit is short-term or long-term let all feed the rate as well. Hurricane risk, which drives coastal premiums in the Gulf and Southeast, is not a meaningful California factor, the state's catastrophe premium is a wildfire and, secondarily, an earthquake and flood story.
Because so many of these numbers vary by ZIP code, fire zone, and carrier appetite, treat any single premium quote as specific to the property. What is dependable is the direction: a rental in a high fire-severity zone will price well above a comparable home in a low-risk suburb, and that gap has widened.
When the FAIR Plan and a DIC wrap enter the picture
When admitted carriers decline a California rental, most often for wildfire exposure, the fallback is the California FAIR Plan, the state's insurer of last resort. It writes owner- and tenant-occupied one-to-four-unit dwellings, including rentals, with residential dwelling limits capped at $3 million.
The catch is scope. A standard FAIR Plan dwelling policy covers fire, lightning, and internal explosion and little else, no theft, no liability, no water damage. To rebuild anything close to full landlord coverage, owners pair it with a Difference in Conditions (DIC) policy that wraps around the FAIR Plan and fills the gaps, including the liability protection a rental needs. The FAIR Plan plus DIC combination is common on hard-to-place California rentals, and it is almost always costlier and more administratively involved than a single admitted policy.
Cost pressure on this segment is real and current. The California Department of Insurance approved a 29.1% average FAIR Plan rate increase that takes effect October 15, 2026, after an estimated $4 billion in 2025 Los Angeles wildfire losses forced a $1 billion assessment on the plan's member insurers. Landlords already relying on the FAIR Plan should budget for that increase and treat it as a signal to re-shop the admitted market whenever a carrier will re-enter their area.
Required / Recommended Endorsements for California
- FAIR Plan policy for high-fire-risk areas where standard carriers have withdrawn
- CEA earthquake policy or endorsement (earthquake excluded from all standard policies)
- NFIP flood or private flood for FEMA flood zones
California FAIR Plan / Specialty Program
https://www.cfpnet.com
The California FAIR plan / specialty program provides coverage when admitted standard market carriers decline to write a policy. Contact the program directly or ask your insurance agent to submit an application. FAIR plan premiums are typically higher than standard market rates, continue shopping admitted carriers annually.
California Insurance Department
The California state insurance department regulates admitted carriers, investigates claim disputes, and maintains a licensed-agent directory.
California Insurance Department →
Written by the NextGen Properties research team. Coverage mechanics reflect standard dwelling fire (DP-3) and homeowner (HO-3) policy forms; California specifics are drawn from the California Department of Insurance and California FAIR Plan (cfpnet.com), including the 29.1% average FAIR Plan rate increase effective October 15, 2026, and the $3 million residential dwelling cap. Flood and mortgage requirements reference FEMA/NFIP and federal lender rules; tax treatment reflects IRS rental-expense guidance. Figures are current as of June 2026. This is general information, not legal, tax, or insurance advice; confirm coverage terms and mandatory requirements with a licensed California agent and your lender.
Frequently Asked Questions
Do I legally have to carry landlord insurance in California?
No California statute requires it. The requirement is contractual: a mortgage lender will require property coverage tied to your loan, and federally backed loans require it outright. If you own the property free and clear, insurance is optional but self-insuring a total loss is rarely wise.
Why can't I just keep the homeowner policy after I rent the place out?
Because it is the wrong policy and keeping it is material misrepresentation. A homeowner (HO-3) policy is written for an owner-occupant. Once a tenant moves in, an insurer can, on a large claim, run a residency check, deny the loss, and void the policy. A DP-3 landlord policy is what keeps your coverage enforceable, and it swaps Loss of Use for Fair Rental Value so lost rent is covered.
What is the difference between DP-1, DP-2, and DP-3?
All three are dwelling fire forms for rentals. DP-1 and DP-2 are named-peril policies that pay only for a listed set of causes. DP-3 is an open-peril form that covers any structural loss unless specifically excluded, which is why most landlords choose it.
Does landlord insurance cover wildfire and flood in California?
A standard landlord/DP-3 policy covers fire, including wildfire, but excludes flood entirely. Flood coverage is a separate NFIP or private policy and is mandatory under federal rules for a federally backed mortgage on property in a FEMA Special Flood Hazard Area. A California FAIR Plan dwelling policy is narrower still, covering fire, lightning, and internal explosion only.
What is the FAIR Plan and when would a landlord use it?
The California FAIR Plan is the state's insurer of last resort for owners who can't get coverage in the standard market, usually because of wildfire exposure. It writes one-to-four-unit rentals with dwelling limits capped at $3 million, but covers only a few perils, so owners typically add a Difference in Conditions (DIC) wrap policy to fill in liability and other gaps.
How much more does a landlord policy cost than a homeowner policy?
Nationally, landlord coverage runs about 25% more than a comparable homeowner policy because insurers price tenant occupancy, vacancy, and liability as higher risk. In California, wildfire exposure can push the cost far above that baseline for properties in high fire-severity zones, so treat any quote as specific to the property, fire zone, and carrier.
Is my landlord insurance premium tax deductible?
Yes. Because a rental is a business, the premium is generally fully deductible as an ordinary operating expense on Schedule E, alongside mortgage interest, depreciation, repairs, and management fees.
Related California Landlord Guides
Hazard data: FEMA National Risk Index (fema.gov) and USGS National Seismic Hazard Maps (usgs.gov/programs/earthquake-hazards). FAIR plan data: NAIC and state insurance department websites. Last updated October 23, 2026. For informational purposes only, not insurance or legal advice. Consult a licensed insurance agent for your specific property and coverage needs.